For investors · Debt Advisory
Acquisition finance for private equity
We structure the debt for your transaction in the DACH region and run the process with the lenders: from the platform acquisition through bolt-ons to refinancing. In the same size class we already advise and sell in.
Situations
We structure the financing of platform acquisitions, add-ons, refinancings and special situations
The questions differ, the craft does not: how much the business carries, who is writing this kind of paper right now, and what the terms actually say.
Platform
Platform acquisition
Financing is part of what wins the deal, not a formality afterwards
When you enter a new portfolio company, the financing sits next to the price. We establish what the target actually supports before the indicative offer goes out, and we collect lender feedback early enough that your bid holds up instead of resting on a financing condition the seller can discount.
Add-on
Add-on and buy-and-build
Add-ons rarely fail on price, more often on the existing documentation
Whether a bolt-on can be paid for out of the existing facility is written into the platform's credit agreement: in the accordion option, in the permitted acquisitions and in the covenants. We read that before the target is approached, then negotiate the upsize or the refinancing.
Refinancing
Refinancing and extension
2027 will be a crowded year
The AlixPartners DACH Debt Report (H1 2026, more than 1,000 companies analysed) puts €151 billion of corporate debt on maturity in 2027. Those borrowers all go to the same market in the same year. Start at maturity and you negotiate in the middle of it. We set the refinancing early enough that extending stays one option among several.
Special
Covenant breach and recapitalisation
A broken covenant is a meeting, not a verdict
When a financial covenant is breached or the plan no longer holds, the quality of the documentation decides how the conversation with the lender ends. We prepare it, run the scenarios and sit through the negotiation on waiver, reset or fresh money. The same applies to a distribution to the fund out of new debt.
Structure
The building blocks of a financing
The mix of instruments decides how much equity stays tied up and how much room you keep across the holding period. A single instrument rarely carries a transaction in this segment.
- 01First rank
Senior bank debt
Lender
House banks, regional and state banks, cantonal banks
The cheapest part of the structure and still the largest in the DACH mid-market. Also the part with the tightest covenants and the firmest amortisation schedule.
- 02One rank, one agreement
Unitranche
Lender
Credit funds
Senior and subordinated debt in a single facility from a single lender. More expensive than a bank, usually without running amortisation, with more room for acquisitions and decidable in weeks.
- 03Behind the banks
Subordinated debt
Lender
Mezzanine funds, development banks
Bridges the gap between what the bank will lend and the equity the fund wants to commit. Part of the interest is often deferred and paid at maturity.
- 04Subordinated, often silent
Vendor loan and earn-out
Lender
The seller
A deferred slice of the purchase price is financing and signal at once: it ties the seller to the numbers shown during the process. For lenders that is an argument, not merely a gap.
- 05Last rank
Fund equity
Lender
You
The figure that ultimately matters. Every layer above it determines how much is tied up and how quickly it comes back.
Process
From debt capacity to drawdown
Step 01
Debt capacity, not a multiple
We work out from adjusted earnings and free cash flow how much debt service the target genuinely carries across the term, capital expenditure and working capital build included. That sets the range you negotiate in, before anyone speaks to a bank.
Step 02
Selecting the lenders
Not every address offering acquisition finance actually serves this size, this sector and this structure. We approach the ones where a yes is realistic. Twenty suitable houses produce more substantive responses than two hundred letters.
Step 03
A package a credit committee can read
The financial model, the credit presentation and the data room are built here. They follow the order in which a committee reviews an application: derivation of sustainable earnings, downside scenarios, security position. Every question answered up front saves a week later.
Step 04
Making the offers comparable
Term sheets arrive in different formats and cannot simply be laid side by side. We translate them into one view: margin and commitment fee, amortisation profile, the definition of earnings that governs the covenants, headroom, accordion option, prepayment penalty.
Step 05
Documentation through to funding
We mirror the credit agreement, the security package and the conditions precedent against the sale and purchase agreement so that signing and closing line up. We stay at the table until the money moves, not until the commitment letter arrives.
The EBITDA definition and the amortisation profile drive the cost
The definition of earnings in the credit agreement governs how much debt is permitted, which adjustments the lender recognises and whether projected synergies from a bolt-on may count. The accordion option decides whether an add-on triggers a fresh negotiation. The amortisation profile ties up free cash flow in the years you need it for acquisitions. The spread moves little by comparison.
None of this sits together in the term sheet. It is spread across the credit documentation. Sort it out only at the drafting stage and you are negotiating under time pressure, in parallel with the purchase agreement. That is the moment you concede things that cost more over the holding period than any spread ever will.
Team
We know the credit committee from the inside: Lukas Knecht ran Structured Finance Switzerland at UBS
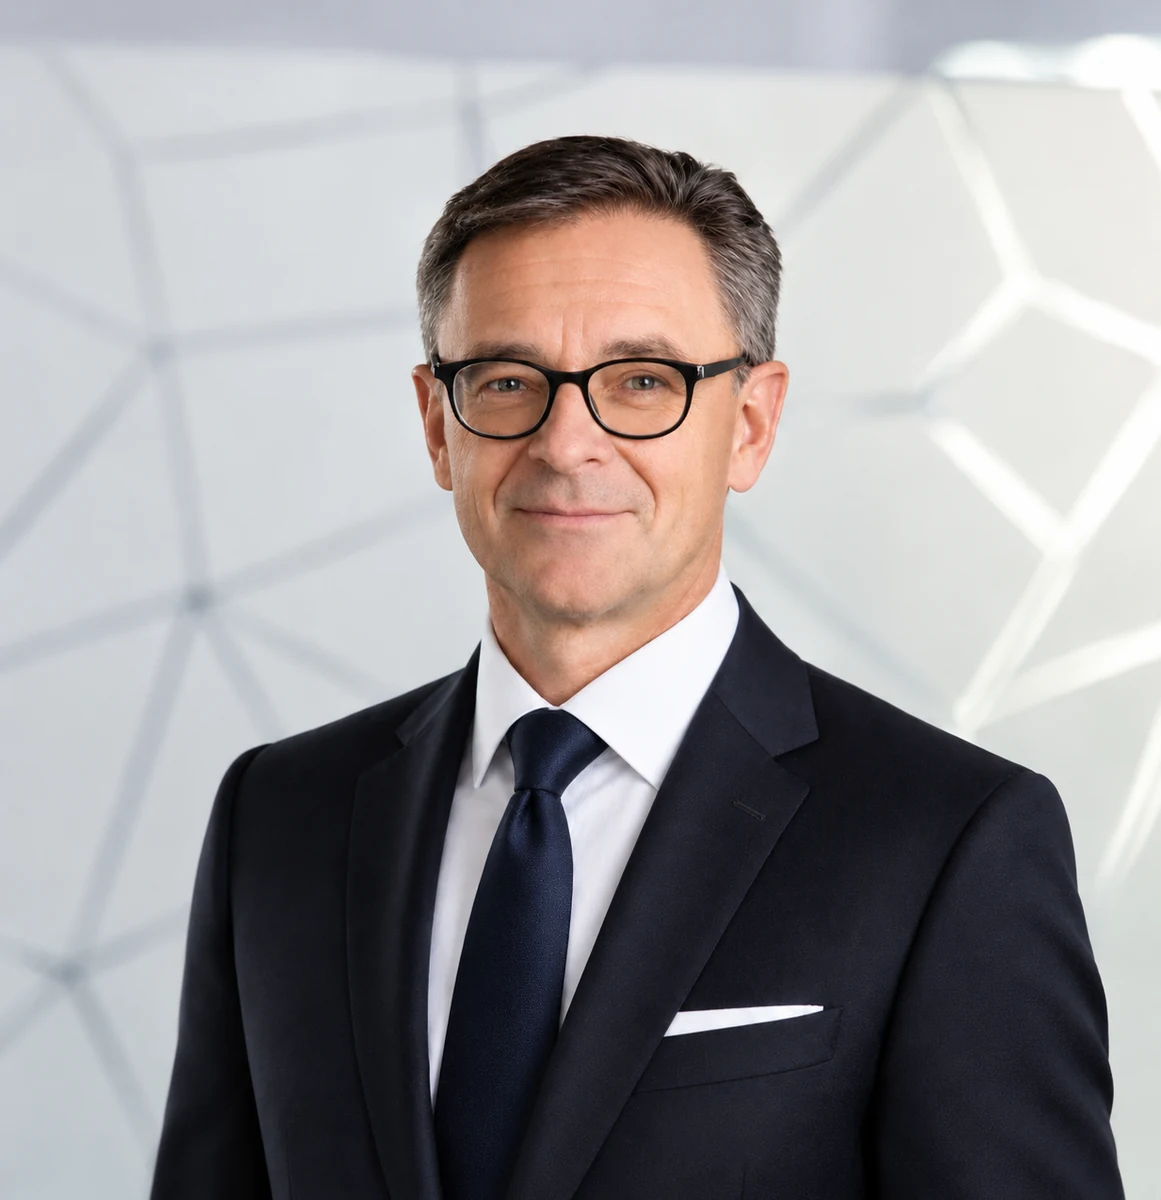
Lukas Knecht was Head of Structured Finance Switzerland at UBS and has spent more than three decades across banking, industry and restructuring, including several years as CFO and executive board member.
He knows the lender's side from the inside: how a credit application is read, which questions a credit committee actually asks, and what a commitment finally turns on. That is the difference between a package that is complete and one that gets approved.
Up to EUR 200m of enterprise value, a transaction is too small for the large banks and too structured for a house bank
Between €5 million and €200 million of enterprise value there is no financing market that explains itself. Part of the target universe is too small for the acquisition finance desks of the large banks and too structured for a classic house bank. Credit funds have moved down into this segment over recent years without covering it evenly, and which house is writing which structure at any given moment changes faster than any list.
That question comes up in our mandates regardless. We prepare the numbers for transactions in this size class, we speak to the investors buying in it, and we see in those processes where financings hold and where they get reopened. Making it a service of its own was the shorter route than continuing to handle it on the side.
How it connects
Other services for investors
FAQ
Frequently asked questions
No, and it would not serve you if we did. A working bank relationship is an asset you do not trade for a few basis points. We put it into comparison so you can see where your house is at market and where it is not. In many cases the same bank ends up lending, on different terms.
We work in the same size class as our other mandates: enterprise values between €5 million and €200 million. Below that, a run process rarely justifies its own effort, and a direct conversation with two or three houses is the faster route. We will tell you when that is the case.
For an acquisition financing with solid numbers, typically eight to twelve weeks from start to drawdown, and longer for a plain refinancing without time pressure. The bottleneck is almost never the lender's decision. It is the state of the documentation at the outset.
No. Some mandates start with a finished structure and a term sheet that wants a second pair of eyes. That is a smaller job than a full process, and we scope it accordingly.
As a normal advisory mandate, scoped to the work. The no-retainer phase model we offer on the sell side does not apply here: it hangs on sale proceeds, and a financing mandate has none. We agree the terms before we start, not afterwards.
Three years of annual accounts, current interim figures, your model and, where one exists, the platform's credit documentation. A first read on debt capacity needs less than that. For that, a conversation is enough.
Contact
Let us get to know each other
A first conversation, in person or remote, with no obligation. We will tell you plainly whether and how we can help.